How NRIs can use UPI from abroad in 2026, explained
What UPI is, why India uses it for billions of payments a month, and how NRIs can use it with an NRE or NRO account and an international number in 12 countries.
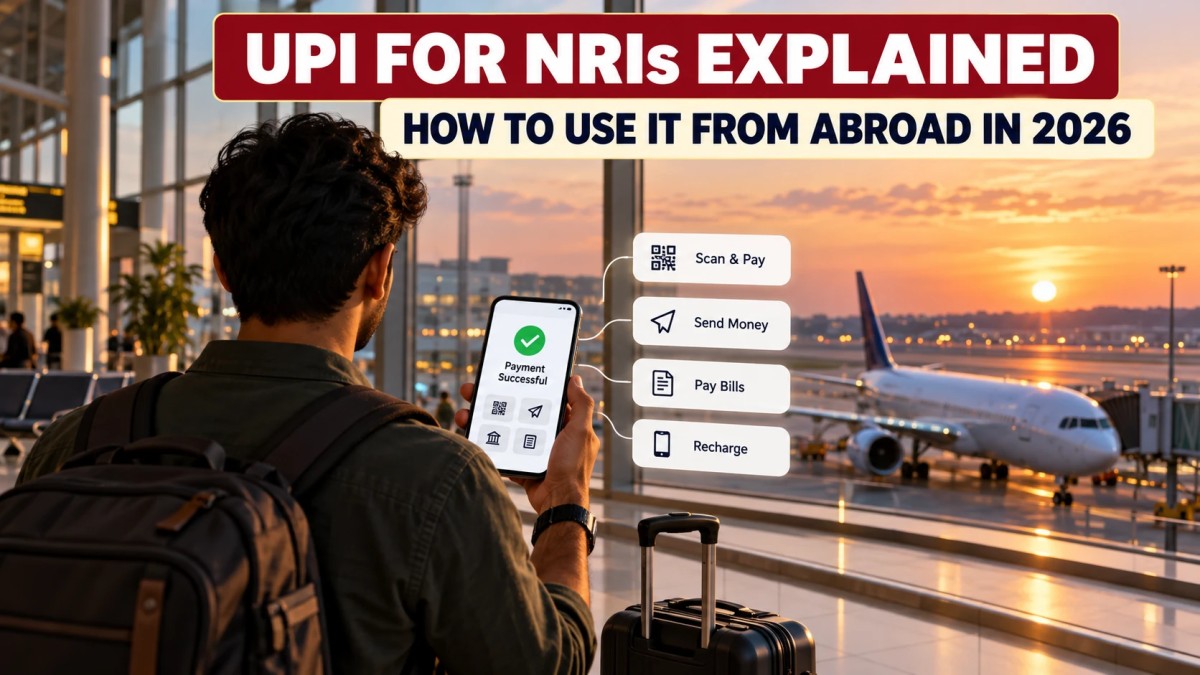
New Delhi (Desk), 18 Oct 2026 (IST) · Explainer
UPI, the Unified Payments Interface, is India's instant payment system: it lets anyone with a bank account and a phone send money in seconds by scanning a QR code or entering a UPI ID. It handled 24.07 billion transactions worth ₹29.37 lakh crore (about $300 billion) in September 2026 alone, according to data from the National Payments Corporation of India (NPCI).
Indians living abroad can use it too. Since 2023, NRIs with an NRE or NRO account can link an international mobile number from a list of countries, now reported to be 12, without an Indian SIM card.
Key points
- UPI was launched in 2016 by NPCI, a body set up by Indian banks under the RBI's oversight.
- It processed an average of about 802 million transactions a day in September 2026.
- NRIs can use UPI with NRE or NRO accounts and mobile numbers from 12 countries, including the US, UK, UAE, Canada, Australia and Singapore, if their bank supports it.
- UPI is also accepted at merchants in some countries, including the UAE, Singapore, France, Nepal, Bhutan, Mauritius and Sri Lanka.
- From 15 October 2026, a 0.4% merchant fee applies to certain payments to merchants above ₹2,000, according to reports; person-to-person transfers stay free.
What is UPI?
UPI is a layer that sits on top of India's bank accounts. Instead of typing an account number and IFSC code, you send money to a UPI ID (like name@bank), a mobile number linked to an account, or a QR code. You approve each payment with a PIN on your phone. Money moves directly between bank accounts, usually in seconds, 24 hours a day.
It's run by NPCI, the National Payments Corporation of India, which was set up by banks with the backing of the Reserve Bank of India. Many apps, from banks and from private companies, connect to it, which is why you can pay a tea seller through one app while they receive money through another.
Why India uses UPI for almost everything
Three things made UPI take off. Person-to-person payments are free. It works between any banks and apps. And a printed QR code costs a shopkeeper almost nothing, unlike a card machine.
After demonetisation in 2016 and the pandemic in 2020, adoption accelerated. Today UPI is used for street-food stalls and electricity bills, rent and train tickets. Daily transactions crossed 800 million for the first time in September 2026, according to NPCI data reported by StartupTalky.
India has also started linking UPI abroad. A link with Singapore's PayNow, launched in 2023, allows instant transfers between the two countries, and NPCI's international arm has partnered with payment networks in several other countries.
UPI for NRIs: how it works
The NPCI allowed UPI for NRIs with international mobile numbers in a circular of January 2023, initially for ten countries. Guides from Indian banks now list 12: the US, UK, UAE, Canada, Australia, Singapore, Hong Kong, Oman, Qatar, Saudi Arabia, France and Malaysia. Countries such as Germany and New Zealand were not on the list as of 2026, according to those guides.
To use it, you generally need:
- an NRE or NRO account with an Indian bank that supports UPI for international numbers;
- your foreign mobile number registered with that bank account; and
- a UPI app that supports your country's code, with your bank listed.
You then set up a UPI ID and PIN as a resident would. Payments come from your NRE or NRO balance, so the usual rules apply: NRE money is repatriable and its interest tax-free in India; NRO interest is taxed.
Not every bank or app supports every country, and features roll out gradually. Check with your bank before travelling, and keep your registered foreign number active, because UPI uses it to verify your device.
The list has grown over time, so check NPCI's website or your bank for the latest countries.
Why it matters: For NRIs, UPI removes one of the oldest frustrations of visiting India: keeping an Indian SIM card alive just to receive banking codes. It also makes it easier to pay family bills, school fees or a plumber in India from abroad, in seconds. For other countries, UPI has become a model of low-cost digital payments that several are now trying to connect to.
Using UPI when travelling abroad
UPI also works the other way: Indian travellers can pay with UPI at some shops abroad, through partnerships between NPCI International and local payment networks. Reported acceptance includes the UAE, Singapore, France (starting with selected locations), Nepal, Bhutan, Mauritius and Sri Lanka. Coverage is patchy and growing; check before you rely on it.
Foreign visitors to India can use a service called UPI One World, introduced in 2023, which provides a prepaid wallet linked to UPI for travellers who don't have Indian bank accounts.
Features you may not know about
UPI has grown well beyond simple transfers:
- UPI Lite is an on-device wallet for small payments, which can be made without entering a PIN each time, useful when bank servers are busy.
- UPI Autopay lets you set up recurring payments, such as subscriptions, insurance premiums or SIPs (systematic investment plans in mutual funds), which you can pause or cancel in the app.
- RuPay credit cards on UPI: since 2022, credit cards on India's RuPay network can be linked to UPI, so you can pay a QR code using credit rather than your bank balance.
- Credit lines on UPI: banks can offer pre-approved credit lines that are used through UPI.
- UPI Circle lets a primary user allow a family member to make payments from their account, within limits.
Availability depends on your bank and app, and some features may not be open to NRE or NRO accounts.
How UPI compares with other countries
Other countries have built similar systems. Brazil's Pix, launched by its central bank in 2020, is the closest comparison and has also become the default way to pay for millions. Many European and US payment systems still rely more on cards, which charge merchants a percentage of each sale. UPI's zero-fee model for most payments is unusual, and its funding is a long-running debate in India.
Fees, limits and safety
Fees. Person-to-person UPI transfers are free. From 15 October 2026, a merchant discount rate of 0.4% applies to specified payments to merchants above ₹2,000, according to reports; payments up to ₹2,000 remain free. The fee is charged to the merchant, not the customer.
Limits. Most UPI payments are capped at ₹1 lakh per transaction, with higher limits for some categories such as tax payments, hospitals and education. Banks may set their own lower limits.
Safety. UPI never asks you to enter your PIN to receive money; if an app asks for it, you're sending money. Scammers often send "collect requests" or fake QR codes that trick people into paying. Never share your PIN or one-time passwords, and verify the name that appears before you approve a payment.
Ten years ago, a family in Bengaluru waited days for money from a son in Dallas, and paid for the privilege. Today the same son can pay their electricity bill from his phone in the time it takes to make coffee. UPI isn't perfect, but few systems have changed ordinary life in India so quickly.
Frequently asked questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Comments (0)